When Moove, the African-founded mobility financing company valued at US$2.1 billion, withdrew from Nigeria in October 2026, its decision exposed a fundamental weakness in one of the continent’s most ambitious approaches to financing commercial vehicles: the assumption that access to a ride-hailing platform could provide a sufficiently dependable stream of income to finance vehicle ownership.
The company’s decision to transfer eligible vehicles valued at approximately ₦35 billion (US$23.3 million, using an illustrative exchange rate of ₦1,500 per US$1) to drivers, while waiving their remaining payment obligations, was an unusual conclusion to a business model built around converting daily transport earnings into vehicle repayments. It also raised questions about the economics of asset-backed mobility financing in markets where vehicle prices, interest rates, exchange rates and operating costs can change considerably over the life of a loan.
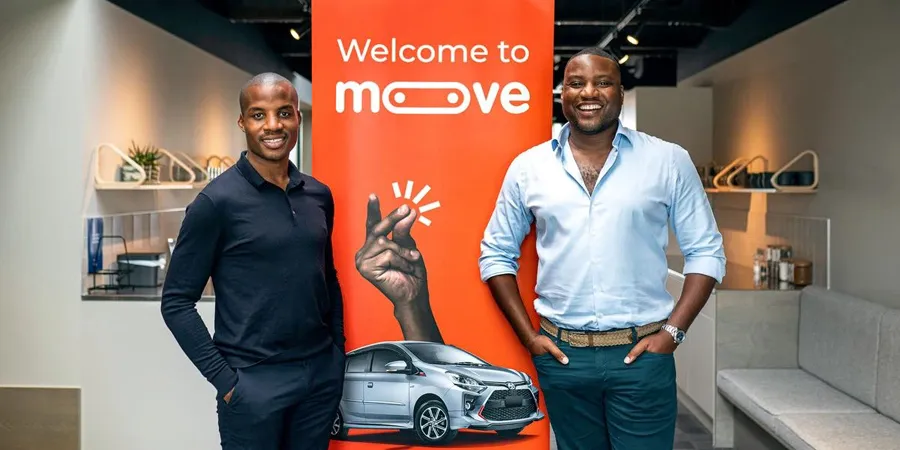
Founded in Lagos in 2020 by Ladi Delano and Jide Odunsi, Moove entered a market where conventional vehicle financing was largely inaccessible to many commercial drivers. Banks generally required substantial deposits, established credit histories and income documentation that informal transport operators frequently could not provide.
Moove offered an alternative. Drivers could access vehicles through rental and drive-to-own arrangements, with repayments linked to income generated through ride-hailing platforms. Rather than relying exclusively on conventional credit assessments, the company could use information about completed trips, earnings and payment histories to evaluate borrowers and manage its exposure.
The proposition addressed a genuine financing gap. Across African cities, thousands of drivers depend on vehicles they do not own, while the cost of purchasing even a second-hand car can exceed several years of disposable income. Vehicle financing therefore offers an opportunity to convert transport work into asset ownership, provided earnings remain sufficient to cover repayments, fuel, maintenance, insurance and the driver’s living expenses.
Moove’s expansion demonstrated the appeal of this model to international investors. In March 2024, Uber led a US$100 million Series B funding round that valued the company at approximately US$750 million. By August 2026, a further US$250 million investment round led by Mubadala, alongside Toyota’s Woven Capital and Ion Pacific, had raised its valuation to US$2.1 billion.
The company had also moved its headquarters to the United Arab Emirates as part of its international expansion, developing operations across several markets beyond Nigeria. By August 2026, Moove reported approximately 42,000 vehicles operating across 29 cities in 13 countries.
Yet the business that had originated in Lagos faced a markedly different operating environment from some of the international markets into which it had expanded.
Nigeria’s currency depreciation increased the local-currency cost of imported vehicles and replacement parts, while high borrowing costs complicated the financing of additional fleet assets. Inflation placed pressure on drivers’ household expenditure, and increases in fuel prices reduced the amount of income available after daily operating expenses.
These pressures are particularly important in drive-to-own financing because the vehicle must simultaneously generate an income for the driver and sufficient cash flow to service the financing obligation.
A vehicle that is commercially productive may nevertheless become financially unsustainable if its operating costs increase faster than the fares earned by its driver. Where the financing provider carries substantial exposure to the vehicle’s purchase cost, repayment difficulties can accumulate across an entire fleet.
The vulnerability becomes greater when vehicle utilization depends heavily on a single ride-hailing platform.
Uber’s withdrawal from Nigeria in September 2026 removed a principal source of demand supporting Moove’s local operations. The company subsequently identified that departure as a decisive factor in its decision to discontinue the Nigerian business.
The episode illustrates the distinction between financing a productive asset and controlling the commercial environment in which that asset generates revenue.
A bank financing a delivery truck ordinarily assesses the borrower’s business, existing contracts, cash flows and ability to obtain alternative customers. In platform-dependent vehicle financing, however, the driver’s earnings may be concentrated within a digital marketplace whose pricing, commissions, operating requirements and continued presence are determined by another company.
The financing provider may own or retain security over the vehicle, but it does not necessarily control the market through which the vehicle earns its income.
This creates a concentration risk that is not immediately apparent from conventional measures of vehicle utilization. Thousands of drivers may appear to represent a diversified financing portfolio, yet their repayment capacity can depend on the commercial decisions of one platform.
When that platform withdraws, the apparent diversification across individual borrowers offers limited protection against a simultaneous deterioration in their earning capacity.
Moove’s decision to relinquish claims over eligible vehicles also highlights the practical limitations of collateral-based lending in mobility finance.
In principle, a vehicle provides recoverable security against a financing obligation. In practice, repossession involves administrative, legal and logistical costs. The lender must locate the asset, establish its condition, recover it, arrange storage and resale, and absorb any difference between the outstanding balance and the proceeds of disposal.
These costs can become substantial when a financing portfolio contains thousands of vehicles dispersed across a large metropolitan area.
Depreciation further complicates recovery. Commercial vehicles accumulate mileage rapidly, and their resale values depend on mechanical condition, maintenance history and prevailing market demand. The value recoverable from a heavily utilized ride-hailing vehicle may be considerably lower than its original acquisition cost.
Moove did not publish a detailed financial breakdown establishing how these considerations influenced its decision to transfer the Nigerian fleet. Nevertheless, the episode demonstrates why vehicle ownership does not necessarily provide lenders with the same protection as readily realizable financial collateral.
The company’s reported ₦35 billion (approximately US$23.3 million) vehicle transfer was also not equivalent to a cash distribution of that amount. It represented the estimated value of eligible assets transferred to qualifying drivers, while the associated repayment waivers depended on the terms of the company’s exit arrangement.
The distinction matters when assessing the financial consequences of the withdrawal. Without information about the remaining loan balances, book values, depreciation provisions and recoverable collateral, the actual accounting loss cannot be determined from the announced vehicle valuation alone.
There is a broader lesson for Africa’s expanding asset-finance industry.
Commercial vehicle financing has increasingly attracted banks, development finance institutions, private credit providers, automotive distributors and technology companies seeking to improve access to productive assets. Their approaches range from conventional hire purchase and leasing to pay-as-you-drive arrangements, digitally monitored fleet financing and revenue-linked repayment structures.
These models differ in their allocation of risk, but they share a dependence on the economic productivity of the financed equipment.
For conventional freight trucks, that productivity may depend on cargo volumes, transport contracts and payment cycles. For agricultural tractors, it depends on seasonal demand, utilization rates and the ability to secure work across different farming areas. For ride-hailing vehicles, it depends on passenger demand, fares, platform access and the driver’s operating costs.
Digital technology can improve the visibility of these activities. Telematics, payment records and vehicle utilization data provide information that conventional lenders previously struggled to obtain. They can support credit decisions, identify maintenance problems and help financiers intervene before repayment difficulties become severe.
They cannot, however, eliminate the underlying commercial risks of the business generating the income.
A vehicle may be continuously tracked, properly maintained and operated by a reliable driver while remaining incapable of generating enough revenue to meet its financing obligations. Equally, strong repayment performance during favourable market conditions does not necessarily demonstrate that a financing portfolio can withstand currency depreciation, rising interest rates or the loss of a principal commercial partner.
The distinction between technology-enabled credit assessment and durable repayment capacity is central to the sustainability of mobility asset finance.
Moove’s international expansion also shows why performance in one market cannot automatically be transferred to another. Vehicle acquisition costs, financing structures, insurance requirements, ride-hailing regulations and consumer purchasing power vary substantially between African cities and markets in the Middle East, Europe and elsewhere.
A financing model that succeeds in a market with relatively stable currency conditions and predictable vehicle residual values may require substantial modification in an economy experiencing rapid depreciation and high inflation.
The Nigerian withdrawal does not establish that drive-to-own financing is inherently unworkable. Moove continues to operate internationally, while other businesses across Africa are developing vehicle leasing, rental and asset-financing arrangements supported by different commercial structures.
What the episode demonstrates is that the viability of mobility financing depends on more than the availability of capital or the sophistication of the technology used to monitor vehicles.
The central financial question remains whether the asset can generate sufficient income throughout the financing period, under conditions that account for operating expenses, depreciation, changes in market demand and the possibility that an important commercial partner may withdraw.
For financiers, this requires attention to the concentration of revenue sources, the enforceability and recoverability of collateral, the resilience of borrowers’ cash flows and the extent to which financing terms can accommodate changes in operating conditions.
For vehicle manufacturers and distributors, it raises questions about the long-term affordability of equipment supplied through financing programmes, particularly where purchase prices are denominated in foreign currencies but customer earnings are generated locally.
For drivers, the eventual ownership of a vehicle can represent a substantial improvement in economic security, but only where the repayment structure leaves sufficient income to sustain both the vehicle and the household dependent on it.
Moove’s exit from its founding market offers a particularly revealing case because it occurred alongside considerable international fundraising and corporate expansion. The company was able to attract capital at a multibillion-dollar valuation while its original Nigerian operating model became commercially unsustainable.
The two developments are not necessarily contradictory. They demonstrate that access to investment capital, corporate valuation and the economics of an individual financing market are different measures of business performance.
In asset-backed mobility finance, the durability of the business ultimately rests not on the number of vehicles financed or the value of capital raised, but on the ability of those vehicles to generate reliable earnings over the full period during which their acquisition costs must be recovered.