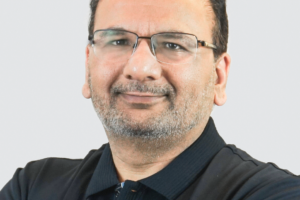
Jeffrey Oppong Peprah: Building the Market Around Ghana’s 5,000-Unit Auto Plant
Volkswagen Ghana already has the plant, the models and the industrial policy framework. Jeffrey Oppong Peprah’s harder assignment is building the market that can absorb what the factory is capable of producing.

- Role
- Chief Executive Officer, Volkswagen Ghana
- Industry role
- President, Automobile Assemblers Association of Ghana; Vice President, African Association of Automotive Manufacturers
- Location
- Ghana
- Mandate
- Local vehicle assembly, market development, financing advocacy and regional automotive growth
The defining problem facing Volkswagen Ghana is no longer whether Ghana can assemble vehicles. It can. The question is whether vehicle finance, industrial policy and consumer demand can develop quickly enough to turn installed manufacturing capacity into a durable automotive industry.
A Production Base Waiting for Demand to Catch Up
The Tema plant demonstrates that local assembly is technically possible. Its utilisation rate demonstrates that industrial capacity alone cannot create an automotive market.
On the edge of Tema’s industrial corridor, Volkswagen Ghana operates a relatively small assembly plant with an ambition considerably larger than its physical footprint. The facility can assemble more than 5,000 cars and pickups a year and is positioned close to the Port of Tema, giving it both logistical advantages and a potential route into neighbouring West African markets.
Jeffrey Oppong Peprah sits at the centre of that experiment. Volkswagen appointed him chief executive when it established its Ghanaian subsidiary in 2020, making him responsible for a business designed not merely to sell imported vehicles, but to participate in the creation of a domestic automotive industry.
The first phase began in Accra with semi-knocked-down assembly. In 2023, Volkswagen shifted into the larger Tema Free Zone facility, creating additional room for expansion and placing the operation closer to the country’s principal seaport. The model range assembled locally has included vehicles such as the Polo, Tiguan, Passat, T-Cross, Amarok and Teramont.
That distinction defines Oppong Peprah’s leadership challenge. By late 2025, Volkswagen Ghana said it had produced more than 2,600 vehicles since operations began. Against annual installed capacity above 5,000 units, the figure illustrates a factory working well below what it could theoretically produce.
The constraint is not primarily manufacturing capability. It is the structure of the market outside the plant. Ghana remains heavily dependent on imported used vehicles, which historically have accounted for more than 70 percent of registrations. For buyers making decisions on immediate cash price, a locally assembled new vehicle is competing against a vast international used-vehicle supply chain.
That leaves Oppong Peprah managing something more complicated than a conventional assembly operation. He is trying to align production capacity with purchasing power, credit, tax policy and a consumer market whose economics have been shaped by used imports for decades.
The Factory Can Build Cars. The Market Still Struggles to Finance Them.
For Oppong Peprah, automotive finance has become an industrial-policy issue because a factory without an accessible credit market will remain structurally underused.
Vehicle finance has become one of the most consistent themes in Oppong Peprah’s public advocacy. Ghana’s car market remains strongly cash-led, making the upfront purchase price disproportionately important. In that environment, imported used vehicles enjoy a structural advantage even when a new locally assembled car may offer stronger reliability, warranty coverage and lifecycle economics.
The difference between Ghana and mature automotive markets is not only income. It is the mechanism through which a vehicle is acquired. Where long-term credit is widely available, households and businesses can spread the cost of a new vehicle over several years. Where rates are high, collateral requirements are demanding and dedicated auto-finance products remain limited, the market naturally gravitates toward cheaper vehicles that can be bought with cash.
As president of the Automobile Assemblers Association of Ghana, Oppong Peprah has argued for a structured financing ecosystem linking banks and local assemblers. The association has pushed for an approach that would make locally assembled vehicles more accessible while creating a more predictable base of demand for Ghana’s emerging manufacturing industry.
Individual partnerships have begun to test the idea. Volkswagen Ghana and GCB Bank, for example, have worked together on financing arrangements intended to improve customer access to new Volkswagens. But Oppong Peprah’s argument reaches beyond one manufacturer or one bank: he has called for a broader national framework capable of changing the economics of purchasing a locally assembled vehicle.
The logic is particularly important for fleets. Businesses make vehicle decisions around cash flow, uptime and total operating cost. Proper finance allows those buyers to compare assets over their useful life rather than treat acquisition as a single large cash event. That is precisely the kind of market structure that can support consistent assembly volumes.
From Assembly Incentives to a Deeper Automotive Economy
Volkswagen’s Ghana investment was built around a national automotive policy intended to establish local assembly. The next stage requires the framework to support scale, localisation and sustained competitiveness.
Volkswagen’s entry into Ghana was closely connected to the Ghana Automotive Development Policy, which created the framework for new passenger cars, SUVs and light commercial vehicles to be assembled locally. Volkswagen Ghana became the first automotive company registered under the programme and began commercial production in 2020.
The policy matters because the economics of small-scale assembly are sensitive to taxation, import treatment and the rules governing semi-knocked-down, enhanced SKD and completely knocked-down production. A factory operating at modest volumes cannot be assessed in isolation from the incentives and regulatory structure designed to make local production viable.
That relationship between policy and manufacturing became more visible in 2026, when the Automobile Assemblers Association of Ghana warned that changes to tax treatment could undermine local assembly. Oppong Peprah, speaking as association president as well as Volkswagen Ghana CEO, argued that removal of key incentives risked weakening an industry still in its formative stage.
The long-term goal, however, has to extend beyond protecting assembly plants. Ghana’s own policy envisages a progression toward deeper industrial capability, including component supply and higher levels of local value addition. The significance of an assembly industry increases when it starts creating demand for parts producers, logistics businesses, technical training, engineering services and skilled employment.
Oppong Peprah has increasingly framed local assembly in those wider terms. A domestic flow of new vehicles can eventually create a more traceable local used-car market, while production at scale can support skills transfer and industrial employment. But none of those benefits becomes automatic merely because an assembly line exists.
The transition requires continuity. Manufacturers have to believe the policy environment will remain investable long enough to justify capital expenditure and localisation. Banks have to see a financeable customer base. Consumers need a reason to shift away from imported used vehicles. Suppliers require sufficient volume before local component production makes commercial sense.
Why Ghana Matters Beyond Its Domestic Vehicle Market
The strategic case for Tema becomes stronger if Ghana can serve neighbouring countries rather than depend entirely on a relatively small domestic new-car market.
Volkswagen has never viewed Ghana solely as a domestic assembly location. The Tema plant’s proximity to the port and Ghana’s position within the African Continental Free Trade Area create the possibility of a West African distribution hub capable of serving markets beyond the country’s borders.
Oppong Peprah has pointed to neighbouring markets including Togo, Benin and Côte d’Ivoire when discussing the regional opportunity. In theory, regional exports can improve plant utilisation by spreading fixed manufacturing costs across a larger addressable market.
The opportunity is significant because many West African markets share Ghana’s dependence on imported used vehicles and relatively small new-car volumes. A regional manufacturing strategy could therefore aggregate demand that is too fragmented when viewed one country at a time.
But regionalisation introduces its own challenges. Trade rules must work in practice, customs and homologation procedures need to align, transport costs must remain competitive and consumers still require affordable financing. AfCFTA can provide the architecture for trade, but it does not by itself create purchasing power.
That is why Oppong Peprah’s role extends beyond the walls of Volkswagen Ghana. His leadership of Ghana’s assemblers association and his wider role within the African Association of Automotive Manufacturers place him inside a continental discussion about how African markets can move from importing vehicles toward building more of the automotive value chain locally.
For Ghana, success will ultimately be measured not by whether vehicles can be assembled in Tema, but by whether local production becomes commercially self-reinforcing: factories creating supply, finance creating demand, policy protecting long-term investment and regional trade expanding the market available to producers.
Volkswagen Ghana
A compact manufacturing operation carrying a much larger test of Ghana’s ability to build a sustainable automotive value chain.
Volkswagen established its Ghanaian subsidiary as part of a wider sub-Saharan African footprint that also includes established or partner assembly activity in markets such as South Africa, Kenya and Rwanda. Ghana became Volkswagen’s fifth assembly location in sub-Saharan Africa when operations began in 2020.
The Tema Free Zone facility, opened in 2023 as an expansion and replacement for the initial Accra operation, has capacity exceeding 5,000 vehicles annually. Its strategic location provides room for further industrial development while placing the plant close to Ghana’s principal maritime gateway.
For Jeffrey Oppong Peprah, the next phase is less about proving that vehicles can be assembled and more about creating the conditions under which assembly can scale. That means working simultaneously on finance, policy continuity, customer confidence, local value addition and access to regional markets.
Local Assembly
SKD vehicle production in Ghana with installed capacity above 5,000 units annually.
Model Portfolio
Locally assembled Volkswagen products have included Polo, Tiguan, Passat, T-Cross, Amarok and Teramont.
Vehicle Finance
Partnerships and industry advocacy aimed at widening consumer access to new locally assembled vehicles.
Industrial Policy
Participation in Ghana’s Automotive Development Policy and the wider debate over incentives, localisation and scale.
Regional Distribution
A long-term ambition to use Ghana as an automotive hub serving neighbouring West African markets.
Industry Leadership
Oppong Peprah combines Volkswagen leadership with representation of Ghanaian assemblers and the wider African automotive manufacturing industry.